This platform serves as absolute, undeniable proof that the redirection of backup withholding taxes from investment banks' 945 payer modules is a fully functioning, legally sound reality.
THE REDIRECTION✦THE 945 PAYER✦THE INVESTMENT BANK✦THE LEGAL REALITY✦THE UNDENIABLE PROOF✦THE PROTOCOL✦ONE CONSTRUCT✦VISUAL PROOF✦AUDIO TREATISE✦THE MECHANICS OF RECOUPMENT✦FOREIGN GRANTOR TRUST✦ALGORITHM 810✦
The Mechanics of
Recoupment
The definitive logic behind the recoupment process, directly addressing the mechanics and legality of 1099-OID filings to bypass Algorithm 810.
What is it?
It is the lawful redirection of backup withholding taxes directly from investment banks’ 945 payer modules. These funds inherently belong to the original creators of the signature—the individuals who signed the mortgages, loans, and credit cards—whose credit was monetized ex nihilo.
How does it work?
Through the creation of a Foreign Grantor Trust (98-Series). Using IRS Form 56, the trust steps into the shoes of the taxpayer (the investment bank). The trust files a 1099-OID because the bank failed to do so. This corrects the record and leverages Rev. Proc. 2002-26 to execute a cross-modular transfer, funding the 945 module to satisfy the match.
Why is it lawful?
Under IRS Publication 1212, if an institution is holding a debt security belonging to someone else, they are operating merely as a nominee. Filing the 1099-OID discharges the debt security. This is explicitly not tax fraud; it is the lawful execution of Holder in Due Course standing over the commercial credit.
Verified Visual Proof
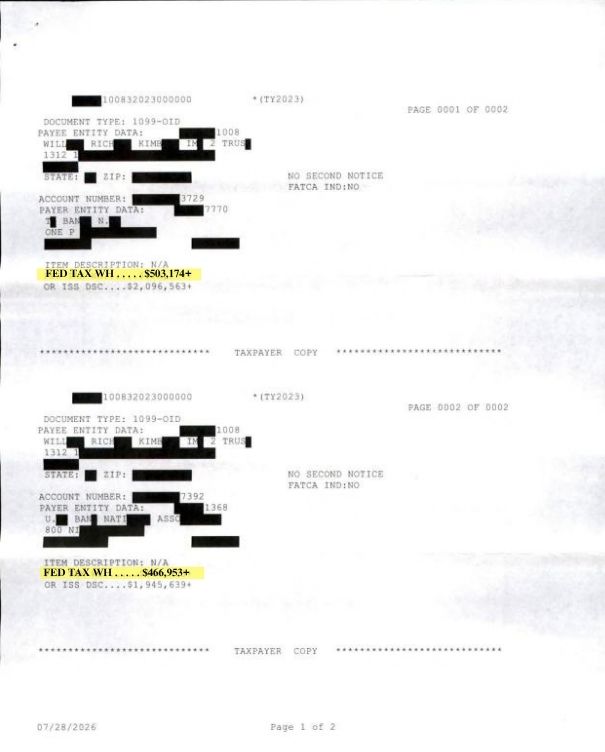
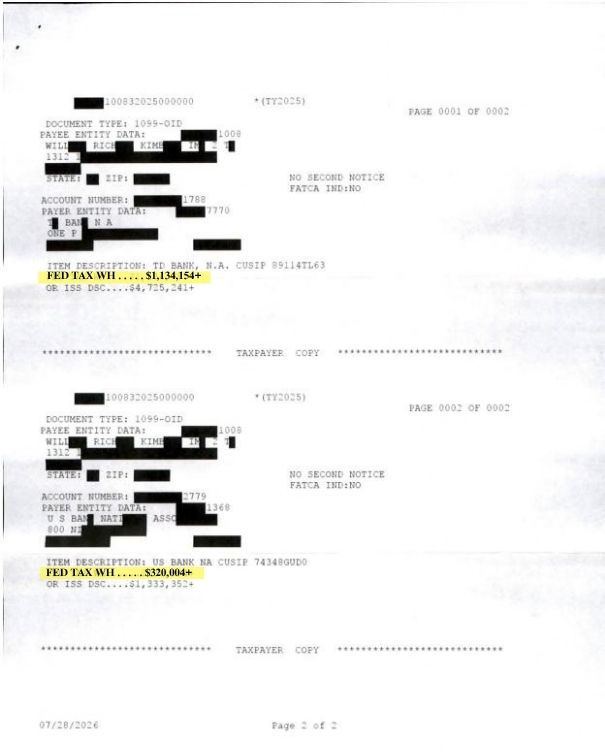
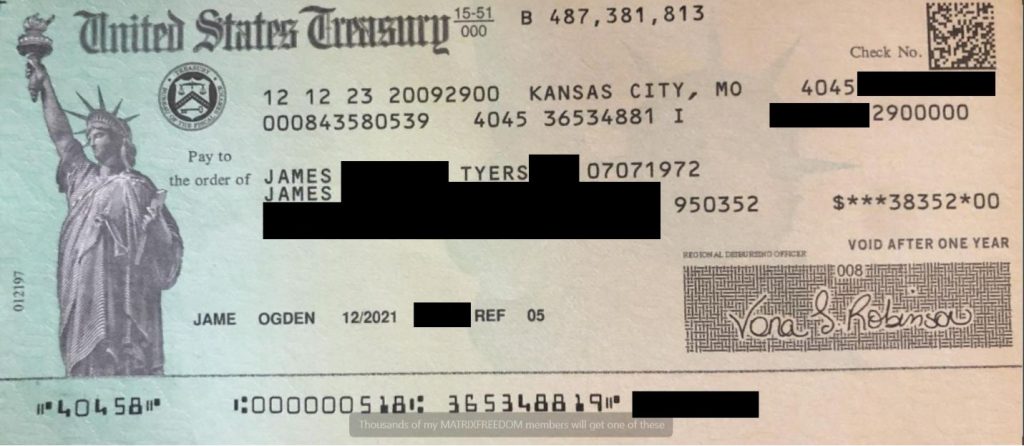
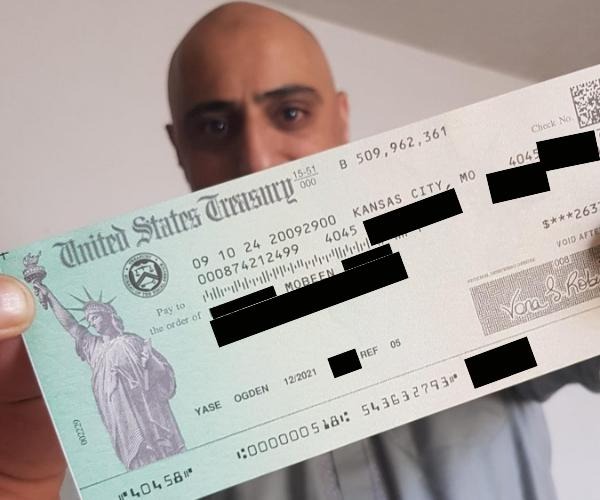
Documentation, IRS Wages & Tax Transcripts, and Treasury Disbursement records validating the passage of Algorithm 810. Over $600 Million confirmed.
02:16:37
Treatise: Signature Credit Tax Redirection
The foundational breakdown of HJR 192, Ex Nihilo credit creation, and Fiduciary standing.
20:23
Tax Transcript Evidence Interview With Ange
Ange works with the ROS tax filing team and evidences the $600million of IRS confirmed signature credit recoupments that were sabotaged in 2025 by Amy Sanger and others